Showing posts with label CleanTech. Show all posts

Tuesday, March 18, 2014

Peeking into the challenges in managing waste water in the tier-2/3 cities in India

In the recently organized 2nd Annual India Utility Knowledge and Networking Conference, experts discussed the Business and Technology Innovations that are the need of the hour for scaling up the Waste Water Management in the tier-2/3 cities in India.

While access to safe drinking water is one challenge that remains to be solved, a corollary and equally significant and impacting health hazard is rising from accumulating municipal & industrial waste water and its untreated disposal. The major issues impacting waste water management are -

  • Cost effective Waste Water Treatment Technology; 
  • By-products use and market development; 
  • Economics and price adoption for Industrial use of treated waste water vs. fresh water; 
  • Public Private Partnerships structuring with clear roles and responsibilities, etc. 

In most ULBs, the reforms are yet to come in. There is still no answer for what to do with recycled water post primary treatment. Often such water is released in nearby water bodies as dissolved impurities in this water can be treated only through RO technology, which is expensive. 

Consider a typical Indian tier 2/3 city with population of 100,000 and about 120-135l water/person/day.  On an average, 80% of the supplied water returns as sewage. At this rate, the city would generate 10mld of sewage per day. 

Experts suggested that installing a 10mld capacity plant with the best in country technology would cost around Rs. 100-130 million i.e. Rs.1300/person investment required. Assuming a 10yrs life of one such plant, the costs come to Rs.130/person/year. This cost plus cost to collect water, suction pump etc put together, recycled water is available at Rs.40/person/month which is about Rs.1.35/person/day. 

If the Government of India considers a country wide investment in waste water treatment, the amount to be raised by government it amounts to (Rs.1.35 x total population of India) per day, which is a huge.


Commercialization of waste water can turn out to be a very useful step in encouraging more industries involved towards treating the waste water. Out 8% of total water supplied to industry, 70% goes to power plants. For Municipal corporations, OpEx still remains an issue since the CapEx is taken care by schemes like JnNURM. Of the total OpEx, 70-80% is the power cost. Without power, it is simply garbage in- garbage out. If power cost is taken care by methods like Group Captive Power Plants (GCPP), the Sewage Treatment Plants could become financially sustainable.

In one such initiative to commercialize and reuse the waste water, Maharashtra State Power Generation Company Limited (Mahagenco) and Nagpur Municipal Corporation (NMC), are jointly installing a 130mld Waste Water Treatment Plant in Nagpur. The NMC will allocate land and subsidy under the JnNURM program and Mahagenco will pay balance amount for project and bear opex. The recycled water would be supplied to Koradi Thermal Plant.

According to Central Pollution Control Board, in tier 2 and 3, only about 20% of total waste water is being treated. Less than 20% WWTPs are being utilized at their 100% capacity i.e.only 5-10% capacity is utilized to treat water. 

This calls for more time being spent on understanding the engineering and technology so as to make the waste water treatment business in India more viable.

====================================================================================
This panel had participation from Jal Board, State Government,. Technology Providers and Project Developers who shared their experiences, and brainstormed to build consensus on shaping an effective and integrated PPP models in Municipal Waste Water Management.

Also read: 

http://timesofindia.indiatimes.com/city/nagpur/Mahagenco-to-give-Rs-15cr-to-NMC-for-waste-water-project/articleshow/3446853.cms

http://timesofindia.indiatimes.com/city/nagpur/660MW-Koradi-unit-countrys-biggest-to-run-on-sewage-water/articleshow/24728967.cms

Friday, December 20, 2013

Jharkhand Rural Distribution Opportunity, Expert Opinions and IUKAN 2014 Updates - Dec, 2013 Newsletter

This is a newsletter for the month of Dec, 2013 sent to mailing list of pManifold sharing Power Distribution Franchisee industry opportunities and updates. 

Some of the recent updates from the Power Distribution Franchisee model are mentioned below. Hope, you find it useful.   

New Opportunities
  • Jharkhand State Electricity Board (JSEB) has floated tender for appointment of Rural Distribution Franchisee in its 8 areas under different sub-divisions. Last date of bid submission is 17th Dec, 2013. (More details can be seen at NITRFPDFA)  
Expert Opinions
  • Views on Managed IT services for Distribution Franchisee by Mr. Ananth Chandramouli, Head - Energy and Utilities, Infosys (Read here)
Trends & Analytics
  • CARE Research recent report on Power Transmission and Distribution indicates Distribution Franchisee as a preferred model for PPP route in the sector (Read here)
Update on IUKAN Annual Conference 2014
  • In the last 2 weeks, me and my colleagues have spoken to industry leaders from over 200+ companies across power and water sectors. The response has been extremely overwhelming especially for the Best Practices Awards being launched with IUKAN. 
  • Online registration for the conference is now open. Early bird registration ends on 1st January, 2014. Use Discount code - IUKAN2014-EARLYBIRD to avail 20% discount.
  • See updated list of IUKAN Advisors here.
pManifold's Utility Practice can be viewed hereIf you would like to know more about us, please contact at kunjan.bagdia@pmanifold.com.

Posted by: Kunjan Bagdia @ pManifold

Wednesday, December 4, 2013

Views on Managed IT services for Distribution Franchisees by Mr. Ananth Chandramouli, Head - Energy and Utilities, Infosys

Mr. Ananth Chandramouli, Head - 
Energy and Utilities, Infosys 
Indian Power market has fast changed and further evolving post unbundling reforms. There is rapid emergence of various private/PPP models across Power Distribution. There is high attractiveness of the end B2C Power Distribution business, as it brings cash for all other businesses in the value chain. The recent surgence of Franchisee models in Distribution has raised the end-service delivery & price value expectations of the end-customers, which is putting more and more pressure on utilities to bring efficiencies and streamline their operations and overall IT.

pManifold team recently spoke to Mr. Ananth Chandramouli, Head - Energy & Utilities, Infosys to understand about their IT solutions Utility-in-a-box (UIB), an innovative cloud-based platform for Utilities. The below shared are author's personal views and not to be associated with any of their company's association.
  1. Please elaborate Infosys’s Utility-in-Box (UIB) IT solution? (phase wise Modules implemented, current deployment stage (whether LIVE), key features, hardware requirements, team size for setup and regular running, business engagement model (Capex vs. Opex based), next planned add-ons, etc.)
    • Infosys UIB is a cloud based solution suitable for Utilities and Distribution Franchisees (DFs). The complete platform including hardware, software, data centre etc. is hosted and managed by Infosys and available on “pay as you go” (opex) model to the Utilities/DFs. Only network connectivity at site and office infrastructure (PCs, printers etc.) has to be procured by the Utility/DF. Infosys has already done capital investment in the state of the art centralized IT infrastructure, which can be shared by multiple DFs/Utilities. This helps DFs in two ways. 
      • First, the CAPEX cost for IT is converted into recurring OPEX cost; this not only provides cash outflow predictability but also reduces the debt/equity investment by DFs.
      • Second, this common infrastructure is designed to be used by multiple DFs hence the cost of hardware, software and services cost are apportioned amongst multiple users. This allows DFs to use this infrastructure at the fraction of the cost that they would have to shell out if they buy such systems at their own.
    • UIB has pre-configured, field tested and optimized processes complying with Indian regulatory requirements so it is fast to implement and can be made up and running in about 3 months either in a big bang or phased manner depending on the readiness of the Utility/DF. This allows DFs to save substantial cost and time. It covers all key utility processes such as Connection Management (New Connection, Change of Name, Meter Shifting, Reconnection, Load Enhancement), Meter to Cash (Meter Reading, Tariff Administration, Billing, Collection), Revenue Assurance and Recovery (Disconnection and Dismantling, Vigilance), Meter Data Acquisition and Energy Audit (Meter Data Acquisition, Meter Data Management, Validation, Estimation and Energy Audit), Customer Care, Work Asset Management and Maintenance Management. 
    • UIB is Smart Grid ready and the next avatar of UIB will have even more features to help Utilities/DFs realize the vision of Smart Grid without making huge investments in IT. Few of these features are - AMI based centralized prepayment, Remote connect/disconnect, Demand Response etc.

Friday, November 22, 2013

PESU DF on-hold, Essel begins Muzaffarpur DF, IUKAN 2014 - Nov, 2013 Newsletter

This is a newsletter for the month of Nov, 2013 sent to mailing list of pManifold sharing Power Distribution Franchisee industry opportunities and updates.

Last month has been slow for Power Distribution Franchisee industry, as 2 opportunities (i.e. PESU Distribution Franchisee and Jaipur's Technical Feasibility Consultant) have seen little progress. Please see below more information about the updates. 

Existing Opportunities
  • PESU bid stands cancelled, as of now. (Read here
Roll Outs & Updates
  • Essel Utilities takes over power distribution in Muzaffarpur, Bihar from 1st Nov, 2013. (Read here)
  • Spanco Nagpur Discom Limited (SNDL) to launch SMS service for complaints lodging and bill updates for its consumers. (Read here)
  • Financial bid opening and evaluation for consultancy assistance to implement Distribution Franchisee in Jaipur Vidyut Vitaran Nigam Ltd (JVVNL) is still due. (Stay tuned for updates)
Indian Utility Knowledge and Networking (IUKAN) 2014

IUKAN is back! Its Bigger...Its Better!!! (Block your dates)

The pManifold team brings to you the 2nd Annual Conference of India Utility Knowledge and Networking forum (13-February-2014 | Le Meridien, New Delhi) with focus on Power and Water Distribution Utilities. The theme for this edition is  'Complimenting Reforms Bottom-up through Improved Operationalization and Engaged Local Ecosystem', with separate focused tracks in Power Distribution (see Power Track Agenda) and Water & Waste Water (see Water Track Agenda).
 
For Best Practice Awards (Get in touch Now to Nominate yourself)

The Awards intend to recognize best practices employed at all business and operating levels of a water, waste water and power distribution utilities thereby driving improve service levels across the industry. If you want to be recognized as the leader in a particular area, then get in touch with us to discuss/nominate. 

pManifold's Utility Practice can be viewed hereIf you would like to know more about us, please contact at kunjan.bagdia@pmanifold.com.

Posted by: Kunjan Bagdia @ pManifold

Tuesday, October 8, 2013

Jharkhand's DF on-hold, PESU bids again extended, MoP New Initiatives, IUKAN 2014 - Oct, 2013 Newsletter

This is a newsletter sent to mailing list of pManifold sharing Power Distribution Franchisee industry opportunities and updates.

Some of the recent updates in the Power Distribution Franchisee space are shared below. Hope, you will find it useful.

Existing Opportunities
Roll Outs & Updates
  • Bids for consultancy assistance to implement Distribution Franchisee in Jaipur Vidyut Vitaran Nigam Ltd (JVVNL) has been submitted by four companies (Crisil, PwC, IL&FS and Feedback). Financial bid opening is still due. (Read here)
  • Jharkhand's Ranchi and Jamshedpur Input based Distribution Franchisee is put 'On-hold', as State Power Minister is planning to conduct an audit to evaluate the feasibility of the model. (Read here)
New Initiatives
  • Ministry of Power (MoP) proposes to bring Management Responsibility for State owned DISCOMs through proposed new bill by state governments to ensure financial and operational turnaround and long term sustainability of electricity distribution. (Read here
  • MoP has recently released 'Smart Grid Vision and Roadmap for India' with an overarching policy objective of Access, Availability and Affordability of Power for All. (Read here)
  • MoP has set up a group that is working on ways to implement the plan which will require a separation of the distribution and the retail supply business, with separate licences for each. (Read here)
Share your vote
  • Should centre mandatorily extend R-APDRP funding to all Franchisee towns to enable better franchisee operationalization and also viability? (Vote here)
Indian Utility Knowledge and Networking (IUKAN) 2014
  • pManifold team is glad to bring 2nd Annual IUKAN 2014 Conference, on 12-13th Feb 2014 at New Delhi. IUKAN 2014 theme is 'Complementing Reforms Bottom-up: Through Improved Operationalization and Engaged Local Ecosystem. (See draft Conference Agenda)
  • One of the distinction of IUKAN 2014 is first of its kind Best Utility Awards to recognize operational best practices and innovations across multiple processes. 
  • On 1st day, we shall be hosting 2-4 parallel workshops, interested Service Providers can connect to us for more details.
pManifold's Utility Practice can be viewed hereIf you would like to know more about us, please contact at kunjan.bagdia@pmanifold.com.

Posted by: Kunjan Bagdia @ pManifold


Tuesday, September 10, 2013

New Report Available: Interim / Mini Power Franchisee Market in India 2013

There are exciting developments in the broader private participation in Indian Utilities in - Network O&M, Customer Services and Revenue improvements. While most heard models are Delhi PPP model; Bhiwandi Input Based Franchisee model; Orissa's Smart metering model; and J&K's new PPP Concessionaire model; a new Interim/Mini Franchisee model is building fast traction.
Alike other models, the Interim Franchisee model is similar turnkey Network, O&M and MRBD Management, but works on much smaller aggregations like malls, townships, SEZ, airports etc. This small volume aggregation comes at much reduced operational & financial risks, offers definite returns, and allows easy entry for new players because of no strict QRs. The model has high scalability in growing Metros and Tier-2/3 towns with multiple aggregations, allowing good economy-of-scale. It also offers high economy-of-scope, as same competence can be extended to undertake broader EE and utility O&M projects.

pManifold Team has dived deeper to research this emerging model and proudly present to you our new report 'Interim / Mini Power Franchisee Market in India 2013'. (See Table of Content and Executive Summary here).

Some add-on top level takeaways and benefits of this report: 
  • This model also known by 'Single Point Connection' is operating in 4+ states (Maharashtra, Haryana, Uttar Pradesh and Punjab) and is poised for fast growth with rapid urbanization and integrated townships development
  • This model has high scalability, and with its proximity and stickiness to clustered end-customers, it could become precursor to bigger Smart Grid and Energy Management Solutions deployment
  • Current service providers in this space are non-organised and fragmented. There is good scope for competent products, solutions and service providers to offer O&M; Metering, Billing and Collection (MBC); Customer Services; Back-up power supply provisioning; and Loss reduction
  • This could be good go-to-market opportunity to build QRs for bigger Input Franchisee projects:
    • Metering, EE and allied product/solution companies to build service portfolio and co-create their offerings with end-customers
    • International players and PE Investors to capture market share of scalable utility O&M Indian business
    • Domestic Infra players to build B2C customer-centric services expertise and QRs

If you would like to know more about the report, please contact at kunjan.bagdia@pManifold.com

Posted by Kunjan Bagdia @ pManifold

Friday, September 6, 2013

Jaipur Franchisee opportunity, Updates from PESU & Dhanbad, Expert Interviews, pManifold's New Report Launch - Sep, 2013 Newsletter

This is a newsletter sent to mailing list of pManifold sharing Power Distribution Franchisee industry opportunities and updates.

Last month, the Power Distribution industry saw various developments across different states. Some of these are mentioned below. We hope you will find them useful.  

New Opportunities
  • Jaipur Vidyut Vitaran Nigam Ltd (JVVNL) has floated a tender for Consultancy assistance to implement Distribution Franchisee in its 3 Discoms namely Jaipur, Ajmer and Jodhpur. 3 discoms have 18 areas for the study. Last date of bid submission is 26th September, 2013. (Read here)
  • Bihar Discom has floated tenders for selection of implementing agency for 'Strengthening, Improvement and Augmentation of Distribution System Capacity" under Backward Region Grant Fund (BRGF) scheme on Turnkey basis. (Read here)

Wednesday, September 4, 2013

Moving from Electrical Contractor to 'Specialised O&M Managed Services Partner' for Power Distribution Franchisees

Mr. Gagan Aggarwal, MD,
Creative Entrepreneurs
Utilities are heavily driven by outsourcing of products and services, but most times, their integration is limited by lack of strong Service Level Agreements (SLAs) and vendor management practices. The new private operators usually start dealing with several products and contractors, and already
scarce Management bandwidth gets occupied in monitoring and renegotiating contracts and performance. The key question here is – can organized vendors be developed with more end-to-end managed services for these new PPPs?

Recently, pManifold team spoke with Mr. Gagan Aggarwal, MD, Creative Entrepreneurs (CE). The company has 30+ years of experience in providing Turnkey EPC and O&M services for Power and Water utilities. The interview focuses upon 'What new business models need to emerge for such managed services that have performance-linked contracts?' The below shared are the author's personal views and not to be associated with any of his company's and other associations.

Sunday, September 1, 2013

Raising meaningful GIS implementation in Indian Discoms and Franchisees

Mr. Sanjay Sahay, VP - India
Sales
GIS is very much talked about in the utility space. Every new franchisee that starts or an existing utility wants to first start by mapping the network and its customers to a GIS map. How effective is this and how effectively it can be done are both questions whose answers differ. However, in the experience of an Indian utility, a well executed strategy for GIS and its integration with existing IT applications can be successfully implemented.

Rahul Bagdia from pManifold team spoke to Mr. Sanjay Sahay, Vice President - India Sales, Infotech - Enterprises. The company has 20+ international experience of providing solutions in the arena of Smart Grid, GIS, Network Management, etc. The below shared are the author's personal views and not to be associated with any of their company's association.

Thursday, August 29, 2013

Bottom-up innovation: From Micro Grid in Indian villages to Smart Grid for urban Discoms

Yashraj Khaitan, Co-founder
and CEO, Grampower
Bringing electricity to rural areas that never may see the grid is a great boon to both people's quality of life and the region's economy. Smart Grid Technology or Renewable Microgrid is the topic of this discussion to improve operational and business efficiency of Indian Power Utilities.
Grampower, a energy technology company is working on addressing the electrification challenges in India. 

pManifold recently spoke to Mr. Yashraj Khaitan, Co-founder and CEO of Grampower. The company sets up energy efficient Smart Microgrids in remote areas to provide on-demand, reliable electricity to telecom towers and rural households with an affordable prepaid purchase model. He has been instrumental in raising over USD1.7 million for the company, and leads product and business development and partnership building to scale the company's operations.The below shared are the author's personal views and not to be associated with any of his company's and other associations.

Monday, August 5, 2013

Franchisee updates from Jharkhand & PESU, Expert Interviews & more - Aug, 2013 Newsletter

This is a newsletter sent to mailing list of pManifold sharing Power Distribution Franchisee industry opportunities and updates.

Some of the recent updates about the industry are mentioned below:

New Opportunities
  • Jharkhand State Electricity Board (JSEB) has floated new RFP documents for appointment of 'Rural Distribution Franchisee' on the basis of 'Collection Based Model' in its 15 sub-divisions comprising of following Area Board: Ranchi, Jamshedpur, Hazaribag. 4 sub-divisions out of 15 are same as per the earlier released tender document in Feb, 2013. The key activities for the participating bidder includes meter reading, billing, collection, minor operation and maintenance of the LT/HT network, attending fuse calls, etc. Last date of bid submission is 27th August, 2013. (Request For ProposalDistribution Franchisee Agreement and Notice Inviting Tender can be read here in details)
  • South Bihar Power Distribution Company Ltd (SBPDCL) has re-initiated tenders through e-procurement mode only for selection of bidders for PESU area. Last date for request of bid document has been extended till 10th Aug, 2013 and for bid submission is 12th Aug, 2013. ('Pre-bid conference replies, RFP and Corrigendum'can be downloaded here)       

Friday, July 19, 2013

Mr. Ajoy Mehta shared his vision on Power Distribution Franchisee models in India

Mr. Ajoy Mehta, MD,
MSEDCL
Mr. Ajoy Mehta, MD, MSEDCL, in a recent Business Technology Conclave of IUKAN extended strong support to Power Distribution Franchisee model, for country to build sustainable power utilities. He shared his experience and vision for further strengthening of the Power DF model. A brief excerpt in form of Q&As from his Vision session at IUKAN is shared below. (The views here are personal views, and not to be associated with any company in any forms)

Q: What role of privatization you see in Indian Discoms?
A: Electricity Act, 2003 made Generation de-licensed, opening to private participation, but in T&D continued to require Licensing, opening it to part-privatization, but not allowing complete private ownership of assets.
  • A Discom performs following core functions 1) sourcing of power 2) tariff filing and reporting to Regulators 3) various customer services like MBC etc. 4) distribution and fault management 5) and HR management.
  • Out of above, sourcing of power & tariff filling and reporting are broadly considered as prerogative of Licensee only, and hence not kept in scope of Franchisee.
  • The strength of private company is to handle customer relationship and bring operational efficiency, and hence remaining above activities including like MBC, IT, and Customer services, O&M, HRM etc. were made in scope of DF.
As Discoms are reeling under the high distribution loss and revenue deficit, the one way of improving the Distribution of electricity is to rightly involve private companies in the sector.     

Friday, July 5, 2013

Leveraging EE programmatic financing for expediting AT&C loss reduction


While Indian Discoms continue to focus on AT&C loss reduction, which in many cases stands to the order of greater than 60%, and lot of private efforts is getting attracted in, it is clear that this is a massive Energy Efficiency (EE) drive. There are various talked instruments for EE financing, but not much has been realised by Indian Discoms. With this Rahul Bagdia from pManifold team spoke to Mr. Vinod Kala, Founder & MD, Emergent Ventures India. He has over 25 years of industry experience, centered on Clean Energy, Strategic Management and Finance. Over the years, he has helped launch a number of new businesses in Clean Technologies including Renewable Energy Aggregators in wind, hydro and bio-mass energy, LED Appliances, Sustainable Farming etc.


This interview focuses upon 'If and how Indian Discoms could leverage & possibly expedite their AT&C loss reduction drive through potential financing from EE programmatic interventions'. The below shared are the author's personal views and not to be associated with any of their company's association.

Tuesday, June 25, 2013

Part 2 of 2 - Suggested amendments in National Tariff Policy

Part 1 of 2 - Suggested amendments in National Tariff Policy

Rahul Bagdia is Co-Founder and Director
of pManifold. The co. specialize in Utilities and
Emerging Markets Research and Advisory,
and is focusing upon operationalisation and improvement in
Service Delivery of Power Distribution models.
Ministry of Power (MoP) is reviewing the Electricity Act 2003 and the National Tariff Policy 2006. 

Federation of Indian Chambers of Commerce of Industry (FICCI) recently had a small group meeting to discuss amendments in these Acts and invited suggestions. 


Mr. Rahul Bagdia, Director, pManifold Business Solutions, shared below suggestions to FICCI team on potential amendments to further create more Market governed healthy power sector in India. These are independent and individual views of the author and not to be associated with any of his affiliation with any company or whatsoever.  

Our existing Policy framework is strong; however its enforcement has been weak. The new amendments in addition to driving more market led changes, should act as better facilitator for measuring performance and enhancing governance in our utilities. Below suggestions are directed in Power Distribution space only.

Sunday, February 3, 2013

Scale-up & Diversify Power Distribution PPP portfolio (Join IUKAN conference - 12th Feb, Delhi)


With developing ecosystem around Distribution Franchisee model (50+ RFPs/EOIs, 22+ start/in-operations in last 2 years), and push for further new roll-outs in light of re-structuring of Discoms, there is need for a careful discussion on scaling-up of right model going forward. It is with this objective that pManifold has organised 'India Utility Knowledge and Networking (IUKAN - www.iukan.in) conference on 12th Feb, Hotel Le Meridien, Delhi'. It shall focus on 'Challenges and Best Practices in Operational Roll Outs of Power & Water Distribution PPPs'. (Download detailed Schedule for topics and Speakers, and overall Brochure).
  • Mr. Ajoy Mehta (MD, MSEDCL), Mr. Mohd. Suleman (Energy Secretary, MP) and Mr. Anil Razdan (Ex. Power Secretary, GoI) will share their reforms journey, and further road map for DF (Good opportunity to influence policy & RFP changes)
  • Tata Power, Enzen, Essel, Spanco, A2Z, SMS groups sharing their Bidding, Roll-outs, Loss Reduction and first year mobilisation learnings (Learn winning bid and practical operational strategies)
  • SBI Caps, IDFC to share risk framework of DF model and its cash flows, and what new financial structuring will increase Debt funding sources (Get linked for your new/existing project's Debt + Equity funding)
  • PTC Financial Services to share its ideas on raising an Aggregator Financial Intermediary, to align various schemes and give Guarantees for attracting primary capital market funding into DF and new PPP models (Get easy access to DF financing for scale-up)
  • CRISIL to share its framework for credit rating of DF project (Incorporate learned KPIs in your Performance Management and reduce interest rates on your term loans)
  • MSEDCL's topmost HR senior to share his handling of Discom employees deputation with 4 DFs in Maharashtra (Understand Discom's perspectives on employee deputation, and engage your employees better)
  • PwC and IL&FS to share learnings from Transaction Advisory and Project Management across different states and projects (Learn best practices in project management of DF)
  • Bescom's MD, NDPL's Chief Commercial Officer, and Essel's Consumer Experience Officer to share their customer engagement strategies that helped them cut losses and improve collections (Learn how the most essential of economic assets, is the health and strength of the company’s relationship with its customers)
  • ABB, Infosys, Secure, IBM, A2Z to share their step forward in offering 'Managed Services Model' to DF and new PPP operators (Engage them and other Vendors participating to build a strong Service Provider Ecosystem, to start with strong domain partners on day one, and low upfront capex)
We assure this is no Generic conference, and is super value-pack with top 30+ Speakers, and 200+ all stakeholders. Best is in addition to Power Distribution, you will learn about equally fast emerging Water PPP models, and further diversify your company's Utility portfolio, more so as same Tier-2 and 3 towns are undergoing both PPPs. (by estimates, India has touched less than 1% market share of PPPs in utilities).

Consider investing in this high quality cross-learning by attending this conference yourself, and also nominating colleagues from your organisation - Corporate Strategy, Bid Team, BU Head, Operations Head, Customer Head, Finance Head, Contracts & Procurement Head.
  • First of its kind conference - you can interact, write to and speak to the Speakers prior to the conference. Infact our Speakers would love this, to get better grounded with DF challenges. (You can write to me your views, and I can appropriately connect you with our Speakers. Time being short, request you make use of this week and weekend for doing this on priority. This way, you can be assured that your views and observations will find importance at the conference.)
  • ZEE News shall be covering the conference, and has interest to speak to Utility veterans. Let know your interest on the same, as it could be good opportunity to rightly position your company's unique efforts to operationalise the DF model. 
I am sure that you and your organisation will stand united and co-own this Industry effort to start re-constructing sustainability in our Utilities, and further improve end-services delivery to customers. 

I and you can (I-U-KAN)! 


Posted by: Kunjan Bagdia @ pManifold

Tuesday, January 1, 2013

I-U-KAN: Raising sustainable Indian Utilities - a unique approach and platform

I-U-KAN (India Utility Knowledge And Forum) is a broader umbrella for all Utilities (Power, Water, Waste, Gas, Transport etc.) and all Stakeholders (Govt., Public utilities, Private Operators, New entrants, Service Providers, Regulators, NGOs, Investors, Customers) to analyse holistic gaps, exchange ideas, build common grounds, and expedite the establishment of sustainable utilities in India.

In this, sustainability is defined in terms of 'three P's’ (i.e. Profit, People and Planet) - so utilities to become Profitable (whoever runs it – Govt. or Private co.); end-customers to get affordable, high quality Services and increased choices; and production & consumption to be optimized for best Environmental conservation.

But, why do we need such an all Stakeholder cross utility platform? Is stakeholder engagement really an issue, and even if it is, then does it have enough weight that it can act as bottleneck to all good efforts? Are there lessons to be learnt from other utilities that can expedite reforms?

To truly figure out whether the various types of stakeholder engagement is missing (if any), let us use an example from the Power Distribution Utility.

1. Central Govt. to Discoms:
R-APDRP, perhaps (in magnitude), holds the position as being one of the biggest infra investment project in the world. Although, the objectives and intentions were great, i.e. invest in Discoms (Distribution Company)  to adopt measurements, automation and Technology to improve loss reduction and enhance accountability. However, most experts would agree that it has not yielded the expected returns.

One major lacuna has been, missing capacity building in the Discoms to effectively use new Infra, tools and right processes. One example is the wasted GIS Customer Indexing effort, which is the first mandated activity for all utility projects. But, because of its inappropriate on-field execution and static nature, it hasn't yield much value in terms of any useful further integration into building strong CRM, and hence timely Revenue Assurance strategies.

Heaps of Energy Audit reports are being compiled, without much care for scientific calibration of metering equipments. And, even if that were to be correct, there is not much measurement based decision making culture in our Indian Utilities. With these weak basic foundation blocks, and missing overall Performance Monitoring, the resulting architecture and operating system continues to remain weak, in spite of Technology influx.

2. Discoms to Private Operators:
The need for increased efficiency in design, development and end-service delivery, huge private investment requirements, and higher accountability, to transform Indian utilities has called for big Change Management. Different models and levels of privatization are being explored such as full privatization (Delhi model); Input Based Distribution Franchisee (Nagpur model); Light capex O&M Franchisee model (Orissa).

However the most basic, the Baseline information of the circle to be privatized (which includes, asset, revenue, costing and other information) is not put up in a robust & credible manner from Discom side. This has lead to irrational bidding, delayed closures, and at times litigation and bid cancellation. And it's not the Discom alone to be blamed, the winning private company at most times, is also not very transparent with respect to its planning related to Capex investments, customer services and employee deputation from Discom. 

Saturday, December 8, 2012

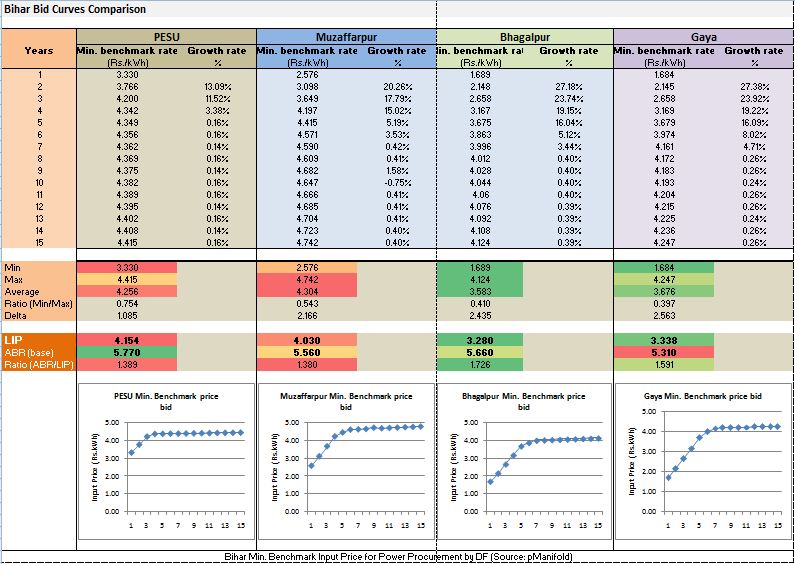
Price bid curves and analytics from Bihar Distribution Franchisee projects

Our earlier blog 'Key amendments in Bihar Distribution Franchisee after pre-bid meeting' covered key points raised in pre-bid meeting and its responses in revised amendments.

Bihar State Power (Holding) Company Limited (BSPHCL) has given minimum benchmark input price curve for all the regions, mandating bidders to bid higher than given price curve for all 15 years. The bidders in pre-bid meeting requested to lower or removed the rates, as current rates to allow them  innovating on financial structuring.

See below table with useful bid analytics (click on the image to see enlarged view):

Some top level observations are:
  • Average growth rate of around 20% in initial first 2 years, with max. in first year; followed by receding growth rate to average 10% by 5 years; almost stable and slow receding of around 0.5% until 15 years
  • Gaya has lowest start point at Rs. 1.684/kWh, with PESU highest at Rs. 3.330/kWh
  • Bhagalpur has lowest end point at Rs. 4.124/kWh, with Muzaffarpur highest at Rs. 4.742/kWh  
  • The ratio of max. to min. rates for each curve is close to 0.4 and above  
    • The highest ratio is for PESU, resulting into lowest delta of Rs. 1.085 between the max and min rates of price curve
    •  The lowest ratio is for Gaya, resulting into highest delta of Rs. 2.563 between the max and min rates of price
  • The Levelised Input Price (LIP) calculated at discount rate of 11.08% is highest for PESU at Rs. 4.154/kWh, followed by Muzaffarpur, with lowest for Bhagalpur at Rs. 3.280/kWh
  • Average Billing Rate (ABR) of Gaya is lowest at Rs. 5.310/kWh, revealing greater improvement opportunity for that DF. On the other hand, PESU has highest ABR of Rs. 5.770/kWh
  • Ratio of ABR to LIP is highest 1.726 for Bhagalpur, 1.591 for Gaya and lowest 1.380 for Muzaffarpur. (This ratio is static indication of profit margin for bidders, with close to 1.00 value is indication of lower margins and higher risks for DF operator)
Posted by: Kunjan Bagdia @ pManifold

Thursday, December 6, 2012

Key amendments in Bihar Distribution Franchisee after pre-bid meeting


BSEB's (hereafter referred as Bihar State Power (Holding) Company Limited (BSPHCL)) organized pre-bid meeting on revised Bihar Distribution Franchisee on 16th Nov. 2012 saw good participation from around 10+ companies. The companies that participated are Reliance Infrastructure, Tata Power, Direct Media Distribution Pvt Ltd, Supreme Infrastructures, Spanco Ltd, Delhi, SPML, CESC, Pan India Network Ltd., Shyam Indus Pvt Ltd, etc. 

This is the third attempt by BSEB to privatize the power distribution in its areas of Patna, Muzaffarpur, Bhagalpur & Gaya. Earlier in 2009, Glodyne Power Limited and CESC were the highest bidder and second highest bidders respectively. Later, CESC became highest bidder as Glodyne was held ineligible for participating in the bid after its partner stepped out of the consortium. In June 2011, BSEB cancelled CESC's bid, saying that it would lose heavily if it awards bid to CESC as the tender was floated in 2009 on the basis of tariff rate of 2007-08. In second attempt, only Essar Power submitted and others refrained from submitting bids due to certain issues on Minimum Benchmarking Price, but as Essar has not submitted formal acceptance within timescale, LOA was cancelled

Saturday, November 24, 2012

Bihar calls again: Revised 4 Power Distribution Franchisees for Patna, Muzaffarpur, Bhahalpur and Gaya

Bihar State Electricity Board (BSEB), after a long gap of nearly 2 years has come back, issuing revised Request for Proposal (RFP) for appointment of Distribution Franchisee for following areas/regions:
  • PESU Area
  • Muzaffarpur town and adjoining areas 
  • Gaya town and adjoining areas
  • Bhagalpur town and adjoining areas
At last, BSEB got a final go ahead from the High Court to re-initiate its privatization initiative for Power supply, which went into long litigation detour with earlier entrusted Essar Power group. Having not received formal acceptance from Essar to its issued LOI in-time, BSEB has cancelled the bid, and issued fresh tender on Oct 22, 2012.

The model is 15 years Input Based DF, with below compared heterogeneity in Network, Consumers and Revenue. Key parameters like Consumer Base, Connected Load (MW), Unit Sales (MUs), Revenue Billed (Rs. Cr.) and Revenue Collected (Rs. Cr.) for all the areas/regions are compared across consumer categories (broadly Residential, Commercial, Industrial (LT & HT), Irrigation).


    Other important parameters like Losses, Average Billing, Collection Efficiency are shown below. Few excerpts from the same are as follows:

    • Input Units is highest for PESU, followed by Muzaffarpur, Gaya and Bhagalpur
    • Transmission & Distribution (T&D) losses is highest for Gaya, followed by Bhagalpur, Muzaffarpur and PESU
    • Collection Efficiency is least for Bhagalpur and highest for PESU
    • Calculated AT&C losses is highest for Gaya, followed by Bhagalpur, PESU and Muzaffarpur.
    Important Dates:
    • A pre-bid meeting is scheduled on 16th Nov, 2012.
    • Last date of submission of Technical bid - 17th Dec, 2012.
    We wish good turnout and rationale bidding for these new coming DF opportunities. pManifold services include for DF turnkey bid advisory including Partner Identification, Technical Due-Diligence, Financial Bid Modeling and Bid Preparation. For more details, contact at rahul.bagdia@pmanifold.com or kunjan.bagdia@pmanifold.com
    RFP can be downloaded from the following link: http://tenders.bih.nic.in/tenderdocs/TD-01-21-10-2012.pdf

    Posted by: Kunjan Bagdia @ pManifold